Quick Answer
- SMSF Dubai property investment is legal under Australian super law.
- The property must pass the sole purpose test with zero personal use.
- Most SMSF Dubai purchases are cash, since lenders avoid foreign property.
- Dubai apartments yield above 7% gross, versus Perth metro near 4.8%.
- Annual valuation, arm’s length dealing, and an independent audit are mandatory.
Perth investors are asking a sharper question in 2026. Can a self-managed super fund buy property in Dubai? The appeal is obvious. Perth metro rental yields sit near 4.8% gross. Dubai apartments now average above 7% gross. Shifting retirement capital offshore looks like an easy win. The truth is more layered than most seminars admit.
SMSF Dubai property investment is legal under Australian superannuation law. The Australian Taxation Office permits an SMSF to hold overseas property. Yet strict compliance rules apply, and several are hard to meet across a border. Structure the purchase well, and the tax benefits are genuine. Structure it poorly, and the penalties are severe. This guide explains exactly how it works.
You will learn the sole purpose test, borrowing limits, and title rules. We explain why most SMSF Dubai property investment deals are cash purchases. You will see which Dubai communities suit super funds best. We also map the real compliance costs for 2026. Every figure here is current. This is the clearest SMSF Dubai property investment guide written for Perth.
What Is SMSF Property Investment?
An SMSF is a private super fund you control as trustee. It lets you choose direct assets, including property. SMSF Dubai property investment simply applies that control to an offshore market.
SMSF Basics
A self-managed super fund holds retirement savings for up to six members. Trustees make every investment decision themselves. The fund is governed by the Superannuation Industry (Supervision) Act. The ATO regulates and audits compliance each year.
More than 616,000 SMSFs now hold around 933 billion dollars in assets. That figure shows how mainstream self-managed super has become. Control is the main draw for Perth trustees. It also brings real responsibility. Every decision must serve retirement, not lifestyle.
Overseas Rules
An SMSF can invest in overseas property under Australian law. The same rules that govern domestic property apply abroad. SMSF Dubai property investment must therefore meet every super obligation. The asset must be held only to provide retirement benefits.
All income must flow back to the fund. The property must be valued at market value each year. Dubai adds one big advantage here. The emirate charges no local property or income tax. That removes the foreign tax drag many other markets carry.
Perth Appeal
Perth property has delivered strong capital growth recently. Local dwelling values rose 24.3% in the year to March 2026. Values also climbed 81.9% over five years. But gross yields remain low, near 4.8%. Net yields fall closer to 3.5% after costs. Dubai offers higher income for the same capital. See how Perth investors earn 8 to 12% yields in Dubai for the full breakdown.
SMSF Dubai property investment blends control, tax efficiency, and higher yield. It is not a shortcut, though. The structure only works when every super rule is followed. The next section covers whether your fund can actually buy.
| Metric | Perth Metro | Dubai |
| Gross rental yield | Around 4.8% | Around 7.15% (apartments) |
| Net rental yield | Around 3.5% | Around 5% to 6.5% |
| Local property tax | Council rates and land tax | None |
| Local capital gains tax | Applies on gains | None |
| Five-year value growth | Plus 81.9% | Strong, area-dependent |
Note: A Dubai property held in an Australian SMSF still reports to the ATO. Australian tax rules apply to the fund regardless of Dubai’s zero local tax.
Can My SMSF Buy Dubai?
Yes, an SMSF can buy Dubai property. But the fund must clear several strict tests first. Miss one and the ATO can make the fund non-complying.
Sole Purpose
The sole purpose test is the single overriding rule. Your fund must exist only to provide retirement benefits. No member or relative can use the property. You cannot holiday in your Dubai apartment. Family cannot stay there, even for one weekend.
Any present-day benefit breaches the test. Penalties range from fund disqualification to heavy fines. This rule catches many hopeful buyers. A Dubai holiday home through super is not allowed. The asset must be a pure investment.
Ownership Title
The fund must hold clear legal title to the property. In Australia, this is straightforward. Overseas, it can be complex. The Dubai Land Department registers property to individuals or companies. It does not recognise an Australian super fund trustee structure directly.
Many funds buy through a compliant holding company instead. Professional structuring advice is essential here. Title is the quiet obstacle most seminars skip. Getting it wrong can void the fund’s ownership. Local legal counsel in Dubai is not optional.
Related Parties
An SMSF cannot buy property from a related party. That includes members, relatives, and their businesses. Residential property also cannot be rented to a related party. All dealings must occur at arm’s length. Rent must be paid at the market rate. Income must go straight to the fund’s bank account.
These rules protect the retirement purpose. They apply to a Dubai asset exactly as to a Perth one. Documentation must prove every transaction is commercial.
| Rule | Requirement | Applies to Dubai? |
| Sole purpose test | Retirement benefit only, no personal use | Yes |
| Related-party acquisition | Cannot buy from members or relatives | Yes |
| Arm’s length dealing | Market-rate rent paid to the fund | Yes |
| In-house asset limit | Maximum 5% in related parties | Yes |
| Annual market valuation | Independent valuation each year | Yes |
Your SMSF can buy Dubai property when these tests pass. The sole purpose test, title, and arm’s length rules all bind. Meeting them offshore takes planning and specialist help. The next question is how you fund the purchase.
How Does SMSF Borrowing Work?
Super funds can borrow only in one narrow way. That method rarely works for overseas property. Here is why most SMSF Dubai property investment is a cash purchase.
LRBA Basics
An SMSF can borrow through a Limited Recourse Borrowing Arrangement. The loan is limited recourse, protecting other fund assets. Each arrangement can hold only one asset. The property sits in a separate holding trust until repayment.
Borrowed funds cannot pay for character-changing improvements. Australian lenders usually require a 20% to 30% deposit. LRBAs are strict even for local property. The rules leave little room for error. Overseas, the barrier is far higher.
Cash Reality
No mainstream lender writes a loan over foreign residential property. Australian SMSF lenders only finance property they can value and repossess. Foreign banks will not lend into an Australian trust structure they do not recognise.
The result is simple. Most SMSF Dubai property investment deals are funded entirely in cash. The purchase draws on the fund’s existing balance. Cash removes leverage from the equation. It also concentrates capital in one offshore asset. Trustees must weigh that liquidity risk carefully.
Currency Risk
Dubai property is bought and rented in dirhams. The dirham is pegged to the US dollar. So your exposure tracks the AUD to USD rate. A weaker Australian dollar lifts your returns in AUD. A stronger dollar reduces them. Some trustees hedge this with forward contracts.
Borrowing is technically allowed but practically closed for Dubai. That makes SMSF Dubai property investment a cash strategy in almost every case. A strong fund balance is therefore essential. Next, we look at which communities suit super funds.
Which Dubai Communities Suit SMSFs?
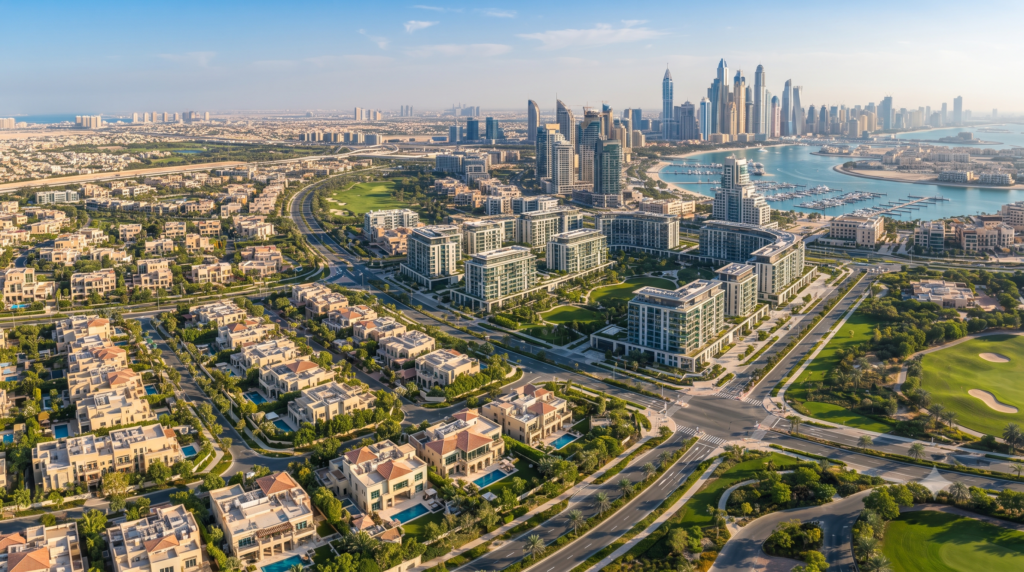
Not every Dubai area fits a super fund. The best area to buy property in Dubai depends on yield, growth, and stability. Here are the communities Perth trustees should study.
High Yield
Mid-market communities deliver Dubai’s strongest yields. Dubai apartments average 7.15% gross in early 2026. Jumeirah Village Circle returns 7% to 9% gross. International City can reach 9% to 10%. These areas suit SMSF Dubai property investment for retirement income.
Entry prices stay lower, which helps cash buyers. High yield means strong cash flow. It also brings more tenant churn. Funds should budget for short vacancy gaps.
Capital Growth
Some communities favour long-term capital appreciation. Dubai Hills Estate and Creek Harbour lead this group. Villa communities have outperformed apartments on price recently. Dubai villa prices rose 9.86% in the year to April 2026. These areas suit funds with a longer horizon. Yields are lower, but stability is higher.
Growth assets build the fund’s balance over time. They pair well with pension-phase planning. Prime areas also hold value through market cycles.
Off-Plan Picks
Off-plan property offers lower entry prices and payment plans. Units often sit 10% to 20% below ready stock. Trusted developers include Emaar, Binghatti, and Ellington. Off-plan suits patient funds with time before retirement. Handover timing must match the fund’s liquidity needs. Explore current off-plan Dubai property listings for live options.
Off-plan can boost total return through early pricing. It also carries construction and timing risk. Fund liquidity must cover the payment schedule.Community choice shapes the outcome of SMSF Dubai property investment. Yield seekers lean to JVC and International City. Growth seekers prefer Dubai Hills and Creek Harbour. Our 2026 Dubai market forecast covers where prices head next.
| Community | Gross Yield | Best For |
| Jumeirah Village Circle | 7% to 9% | Income and cash flow |
| International City | 9% to 10% | Maximum yield |
| Dubai Hills Estate | 5% to 6% | Capital growth |
| Dubai Creek Harbour | 5% to 6% | Long-term growth |
| Business Bay | 5.5% to 7% | Balanced returns |
Community choice shapes the outcome of SMSF Dubai property investment. Yield seekers lean to JVC and International City. Growth seekers prefer Dubai Hills and Creek Harbour. Our 2026 Dubai market forecast covers where prices head next.
What Are The Compliance Costs?
Running an SMSF Dubai property investment is not free. Several costs recur each year. Budgeting for them keeps the fund compliant.
Setup Costs
Establishing an SMSF involves trust deed and registration fees. A corporate trustee adds an ASIC setup cost. Offshore purchases add legal structuring fees in Dubai. Title and holding company setup can be significant. Most experts suggest a fund balance of 200,000 dollars or more.
SMSF Dubai property investment often starts working near 250,000 dollars. Setup is a one-time hurdle. Doing it properly avoids future breaches. Cutting corners here is a false economy.
Annual Duties
Every SMSF needs an independent audit each year. That audit is legally required. Annual running costs range from 2,000 to 7,000 dollars or more. Costs include accounting, audit, and the ATO supervisory levy. Overseas assets raise audit complexity and valuation costs. An independent Dubai valuation is needed each year.
Offshore property lifts the admin burden. Foreign valuations and records take extra effort. Good bookkeeping keeps audits smooth.
Tax Position
SMSF tax rates are the real advantage. Accumulation-phase income is taxed at 15%. Capital gains are effectively 10% after twelve months. In the pension phase, both fall to zero. Dubai adds no local tax at all. So pension-phase Dubai income can be fully tax-free. A licensed SMSF specialist should confirm your position.
The tax gap versus personal ownership is wide. High earners benefit most from the 15% rate. From 1 July 2026, balances above 3 million dollars face extra tax.
Compliance costs are the price of these tax benefits. For the right fund, SMSF Dubai property investment still stacks up well. The numbers favour long horizons and higher tax brackets. Always model the plan with a licensed adviser first.
| Cost Item | Frequency | Typical Range |
| SMSF setup (deed, registration) | One-time | Around 1,000 to 3,000 dollars |
| Corporate trustee (ASIC) | One-time plus annual | Setup plus annual review fee |
| ATO supervisory levy | Annual | 259 dollars |
| Total annual running costs | Annual | 2,000 to 7,000 dollars plus |
| Dubai property valuation | Annual | Independent valuer fee |
Grow Your SMSF With Dubai Real Estate
SMSF Dubai property investment offers Perth investors a rare mix. It combines control, high yield, and strong tax efficiency. Dubai apartments out-earn Perth property on income by a wide margin. Add zero local Dubai tax and the case grows stronger. For the right fund, the numbers are compelling.
SMSF Dubai property investment still demands discipline and expert help. The sole purpose test, title rules, and cash-only reality are non-negotiable. Compliance costs and annual valuations must be planned. This path suits funds with a healthy balance and a long horizon. Always confirm your position with a licensed SMSF specialist first.
Your retirement capital deserves a market that pays more, and Dubai delivers exactly that for Perth investors. Register your interest today at Dubai Property Expo Perth to meet verified developers and plan a compliant SMSF purchase.
Frequently Asked Questions
Can an SMSF buy property in Dubai?
Yes. An SMSF can legally buy Dubai property under Australian law. The ATO permits overseas property when the fund follows super rules. The asset must pass the sole purpose test. It must be held only for retirement benefits. No member or relative may use it. The fund must also hold clear legal title, which needs careful structuring in Dubai.
Is Dubai rental income taxed inside an SMSF?
Dubai charges no local tax on rental income or capital gains. That is a major advantage over most overseas markets. However, the income still belongs to your Australian SMSF. In the accumulation phase, fund earnings are taxed at 15%. In the pension phase, the rate falls to zero. So a pension-phase Dubai property can produce fully tax-free income for members.
Can SMSF Dubai property qualify for a Golden Visa?
Usually not for the individual member. The UAE Golden Visa requires personal property ownership of at least 2 million dirhams. Property held by your SMSF is owned by the fund, not by you personally. So the member is not the registered owner for visa purposes. Investors who want the visa often buy personally instead. You can compare both routes in our Dubai Golden Visa property guide.
How much super do I need for a Dubai property?
There is no legal minimum SMSF balance for property. Most specialists suggest at least 200,000 dollars to cover costs and buffers. For Dubai, the maths often works from around 250,000 dollars. Because most SMSF Dubai property investment is cash funded, the fund needs the full price available. Trustees should keep a liquidity buffer for fees and pension payments. Modelling the numbers first is essential.
Can my SMSF borrow to buy Dubai property?
In practice, no. Borrowing must use a Limited Recourse Borrowing Arrangement. No mainstream lender writes such loans over foreign residential property. Foreign banks will not lend into an Australian super fund structure either. As a result, nearly all SMSF Dubai property investment is cash funded. This removes leverage but also lowers loan risk.